A one-month statutory deadline has left a NSW retail tenant without the market rent review it expected to receive. Robert Speirs, examines the Southcity Shopping v SC Pharm Services decision and argues that the legislation’s blunt approach prioritises speed over getting a fair valuation outcome. Readers may recall that in recent commentary I have been a tad critical of the Retail Leases Act 2003 (RLA) in Victoria. This does not mean the other jurisdictions have got it right. In NSW, the New
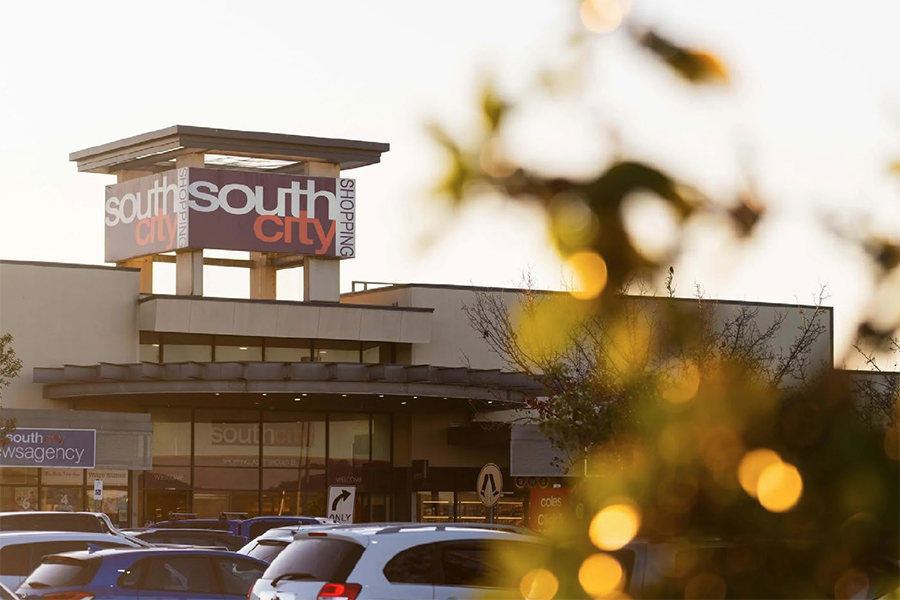
South Wales Civil and Administrative Tribunal (NCAT) has just delivered a solid judgement in which the tenant has again been sacrificed to ill-conceived statutory protection. The case is Southcity Shopping Pty Ltd v SC Pharm Services Pty Ltd [2026] NSWCATCD 106, and concerns a market rent determination under s32A of the RLA.
Section 31 of the RLA provides that where a lease provides for a market rent review and the landlord and tenant are unable to agree, the market rent is to be determined by a “specialist retail valuer” appointed by the Registrar. Section 32A then goes on to provide that a party to a lease may apply to the Registrar to appoint two specialist retail valuers to conduct a review of the determination made by the single specialist retail valuer appointed under s31.
Sections 32A (6) and (7) were at the heart of the decision:
“(6) The specialist retail valuers are to conduct the review and reach their decision not later than one month after they are notified of their appointment.
(7) If the specialist retail valuers are unable to agree by the end of the month referred to in subsection (6), the valuers are taken to have decided to affirm the [original] determination.”
Pausing here, it goes without saying that a market rent review is of critical importance to the parties to a lease.
The market review sets the baseline rent for the ensuing term, from which subsequent fixed or CPI reviews tee off. As such, the determination of the market rent could make the difference between success or failure for the business conducted by the tenant from the leased shop. It is of equal importance to the landlord, since it feeds directly into the income derived from the real estate, and the cap rate for valuation purposes.
Given the serious and long-term implications of the market rent review, you would expect the legislation to establish a process for getting the ultimate valuation right, or as right as is possible for an inexact science.
The Southcity case gave the statutory machine a road-test.
As it happened, the landlord and tenant could not agree on the market rent. A specialist retail valuer was appointed, and determined the market rent under s31. The tenant was unhappy with the determination, and activated the review mechanism under s32A. The Registrar duly appointed two specialist retail valuers.
The two valuers did not commence, let alone complete, the valuation review within one month of their appointment. Instead, they concerned themselves with procedural issues and the not unimportant question of payment of their fees. After months of procedural back and forth, the two valuers finally arrived at a determination, which was not to the landlord’s liking. The landlord then commenced the NCAT proceedings on a number of grounds, the important ground being that because the valuers had failed to agree within a month of their appointment, they were taken to have affirmed the original valuation in accordance with s32A(6) and (7) quoted above.
The tenant argued (based on the earlier ADT decision in Kokkinidis v Zaharopoulos [2011] NSW ADT 153 that the phrase “unable to agree” in s32A(7) requires an active disagreement, and that time does not begin to run under s32A(7) unless the valuers have attempted to agree and failed.
The Tribunal held that it was not bound to follow Kokkinidis as precedent, and [at 66] that as a matter of plain English, the phrase “unable to agree” is capable of referring either to actual disagreement or to a state of affairs in which the relevant result has not been achieved within the time available.
As a matter of statutory construction, it was also clear to the Tribunal [at 68-72] that under s32A(6), time would start to run from notification of the valuers’ appointment, not from some subsequent unspecified time when the valuers had sorted out their procedural issues.
It was also important that s32A(7) set a clear and express consequence flowing from a failure to agree within the one month following appointment. That is, absent agreement by the two valuers within one month of appointment, the original valuation is to stand.
In the present case, because the valuation by the two valuers was not delivered within one month of appointment, (and sometimes you have to love dead languages) the valuers were held to be functus officio, meaning that they had no work to do, and the original valuation stood.
I have no argument with the decision in this case, but it demonstrates that s32A is a difficult bike to ride.
When you think about it, it is perfectly reasonable for the two valuers, once appointed, to make arrangements for payment of their fees, to make procedural arrangements for the conduct of their review, and to obtain market data or submissions before completing their review. But those tasks must be performed at the peril of the statutory one-month stopwatch. The effect would appear to be that the party with the favourable original valuation could frustrate the two-valuer process by simply failing to comply with requests for information or security for costs.
The alternative appears to be that the Registrar should defer appointing the valuers until all of those preliminary issues regarding security for costs and process have been sorted out. But then you suffer the same problem that the party with the happy valuation will be unresponsive, and the Registrar will fail to launch.
What we have in this case is a tenant who was murdered on the initial market rent determination (at least in the eyes of the tenant) being, in effect, deprived of the statutory review by the procedural ineptitude of the statute.
What happens if the valuers:
(a) need to pause because a question of law arises, which needs to be resolved before they complete the task?
(b) get the flu and are unable to perform?
The answer must be that the original valuation stands.
What happens if the original valuation comes in at $100, and the two valuers are unable to agree, because one of them thinks the valuation is $500 and the other thinks $400? Clearly, the original valuation is out of whack, but it will stand even though it appears that the true valuation is around $450. (You would hope that the two valuers would agree to split the difference and agree on $450, but that is not a foregone conclusion).
It follows that the enactment is a blunt instrument, and that the drafting is misconceived.
While it appears snappy and superficially attractive to impose these sexy deadlines, the effect is that the process is doomed to fail. Given the massive, long-term consequences, it is clearly more important to the parties to get it right than to get it fast.
Southcity demonstrates that s32A was not thought through before enactment. It provides yet another example of ill-considered retail lease legislation protecting a landlord at the very considerable cost of the tenant. It is yet another example of the disease being better than the cure.
This article by Robert Speirs was first published in SCN magazine.

Add comment